Loading
Related Articles
Related Articles

TrustFinance
Sep 17, 2026
6 min read
24

Slippage is the difference between an identified reference price and the price at which an order actually fills. Buying lower or selling higher is favourable; the reverse is adverse. An ordinary stop loss can execute beyond its trigger. To investigate a trade, establish the price side, benchmark, quantity and completed status. Leveraged Forex products can cause substantial losses.
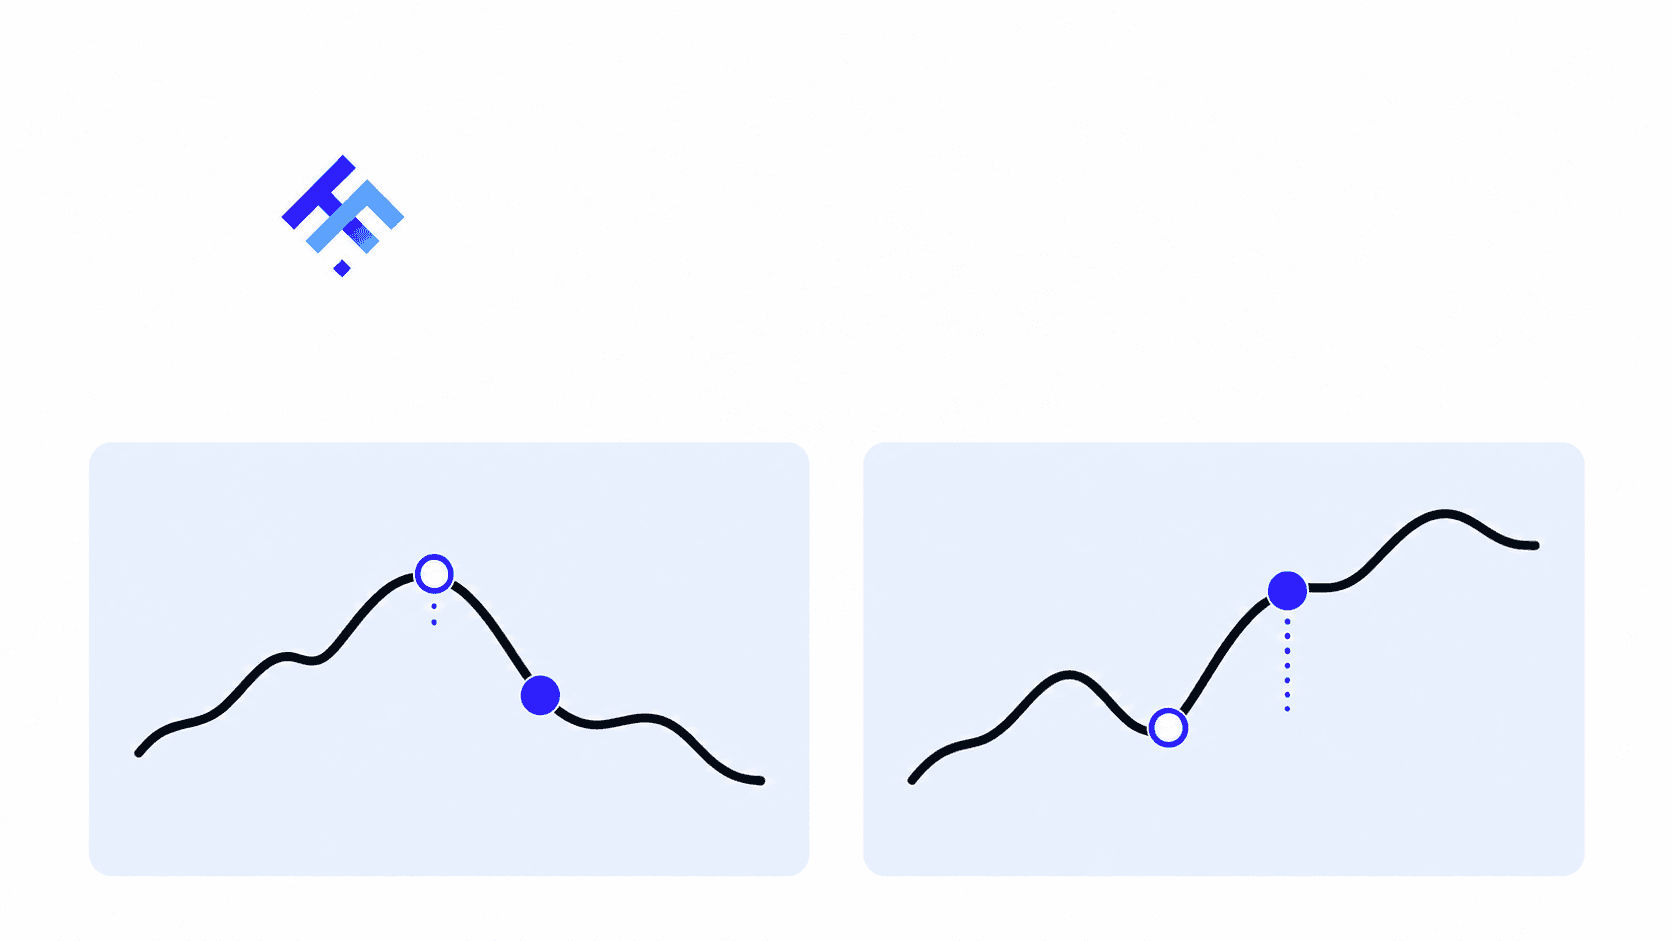
A screen quote, requested limit, stop trigger and completed fill are different records. State which reference you compare. A mid-price chart is not automatically the bid used to sell or the ask used to buy. Keep the quote, order and fill times. A screenshot alone cannot reconstruct the provider’s executable price.
Use a side-aware convention: adverse buy difference = fill minus reference ask; adverse sell difference = reference bid minus fill. Divide by pip size to obtain pips. A negative result under this convention is favourable, often called positive slippage. It does not mean the entire trade is profitable. For multiple fills, use the quantity-weighted average fill and the same executed quantity.
Assume EUR 10,000, a USD account and one pip = 0.0001 USD per EUR, worth USD 1 per pip for this position. Initial bid is 1.1000 and ask is 1.1002, a 2-pip spread. Each row is a separate invented execution scenario, not historical quotes or broker performance.
| Scenario | Reference | Assumed fill | Execution difference |
|---|---|---|---|
| Buy, adverse | Ask 1.1002 | 1.1005 | 3 pips worse; USD 3 extra cost |
| Buy, favourable | Ask 1.1002 | 1.1001 | 1 pip better; USD 1 lower cost |
| Sell, adverse | Bid 1.1000 | 1.0997 | 3 pips worse; USD 3 fewer proceeds |
For the adverse buy, (1.1005 - 1.1002) / 0.0001 = 3 pips, and 0.0003 × 10,000 = USD 3. The favourable buy saves USD 1 against its reference ask. For the adverse sell, (1.1000 - 1.0997) / 0.0001 = 3 pips, meaning USD 3 fewer sale proceeds. Lower prices favour buyers but disadvantage sellers.
Suppose the adverse buy fills at 1.1005 and immediately closes in full at an unchanged bid of 1.1000, with no additional closing execution difference. Price loss = (1.1005 - 1.1000) × 10,000 = USD 5. In this fixed example, it contains the initial 2-pip spread plus the 3-pip adverse buy difference. Do not add spread again to a loss already measured from entry ask to exit bid.
The example excludes commission, financing, conversion, taxes, other price changes and earlier margin closeout. Monetary pip values depend on pair, quantity and account currency. A gap compares successive market prices; slippage compares reference and fill. Neither alone gives total trading profit or loss. Margin liquidation is a separate account mechanism.
Prices, liquidity, order size and processing time can change executable prices. News or reopening may expose these factors, but no session or event guarantees slippage. Large orders may use several price levels. OANDA Asia Pacific describes bid/ask VWAP and latency in its specific execution documentation.
Distinguish requotes, rejections and cancellations from completed fills. A proposed replacement price never executed has no fill-price slippage to calculate. An acknowledgment does not prove the requested quantity traded. Actual terms and the order report matter more than an instant or market execution label.
Do not group ordinary stops with price-constrained limits. IG UK warns that a normal stop can fill worse. Hypothetically, a sell stop triggered at 1.0950 fills at 1.0946 for EUR 10,000: the adverse difference versus trigger is 4 pips or USD 4. This is not total trade loss or a maximum-loss guarantee.
| Instruction | Price condition | Remaining limitation |
|---|---|---|
| Market | Available price under the contract | Price, size and execution remain conditional |
| Ordinary stop | Trigger activates an execution instruction | May fill worse; trigger is not a completed fill |
| Limit | If filled, limit price or better | May remain unfilled or fill only partly |
| Stop-limit, if supported | Trigger submits a limit instruction | Price restriction can leave exposure open |
| Eligible contracted GSLO | Specific contracted stop-price protection | Premium and restrictions; other risks remain |
OANDA UK describes eligible GSLOs as a distinct product with premiums and restrictions, not ordinary stops or account-wide safety. Optional price bounds are platform-specific and may cancel an order outside tolerance. OANDA Asia Pacific explains stop-limit but lists it unavailable on its listed platforms. Verify actual support.
A difference alone neither proves misconduct nor rules it out. A query needs records and applicable terms. This guide does not determine a legal dispute.
No. Where supported, a bound may prevent an unacceptable fill by leaving the order unexecuted. A canceled or rejected closing instruction can leave the position exposed.
No. It is favourable only relative to the selected reference. Later prices, other fills and costs can still produce losses.
This is general education using editorial assumptions, not trading advice or a provider recommendation. ASIC Moneysmart’s Australian education explains leverage and execution risks. Australian rights cannot be assumed for other entities; product, contract and jurisdiction determine conditions.
Official sources checked on 14 October 2026. Singapore and UK examples describe specified entities or products, not universal availability.
OANDA Asia Pacific means OANDA Asia Pacific Pte Ltd in Singapore; OANDA UK means OANDA Europe Limited. The IG source describes its UK product sections. These provider examples do not establish the terms of your account.
TrustFinance
TrustFinance helps financial companies build credibility and traders make safer choices through verified profiles, authentic reviews, and research-driven insights.